

A simple way to see how insurers view you is to enter your details accurately and compare quotes. The prices you’re shown are each company’s own take on the risk, and that can differ quite a bit from one insurer to another.
Car insurance pricing is built from many moving parts
Some of the many factors affecting your premium
Insurers consider the driver, vehicle, address, use, mileage, claims history and cover selected. Each insurer combines these details in its own way.
Your job title and working pattern
Occupation is one of the details insurers consider. It can influence how risk is assessed because different jobs tend to involve different driving patterns, mileage and parking arrangements.
For example, someone who drives between multiple sites each day presents a different profile from someone who commutes a short distance and parks on a driveway overnight. Shift work, business use and tool carriage may also influence underwriting decisions.
But occupation rarely works on its own. An insurer may offer a good rate for one job, but then charge more because of the postcode, the car, or another detail in the overall profile.
Postcode and where the car is kept
Claims data varies across the country, and insurers analyse local trends such as accident frequency, theft rates and repair costs. Even neighbouring postcodes can be rated differently. Location plays a significant role.
On-street parking in a busy area presents a different exposure from a locked garage or private driveway. These details feed directly into risk calculations. Where the vehicle is kept overnight also matters.
The car itself
Vehicle type, engine size, performance, repair cost and parts availability all influence premiums. Cars are grouped according to insurance rating categories, but insurers may interpret those groups differently.
A modest family hatchback is typically assessed differently from a high performance model. Safety features, modifications and vehicle value also form part of the underwriting picture.
Your driving history
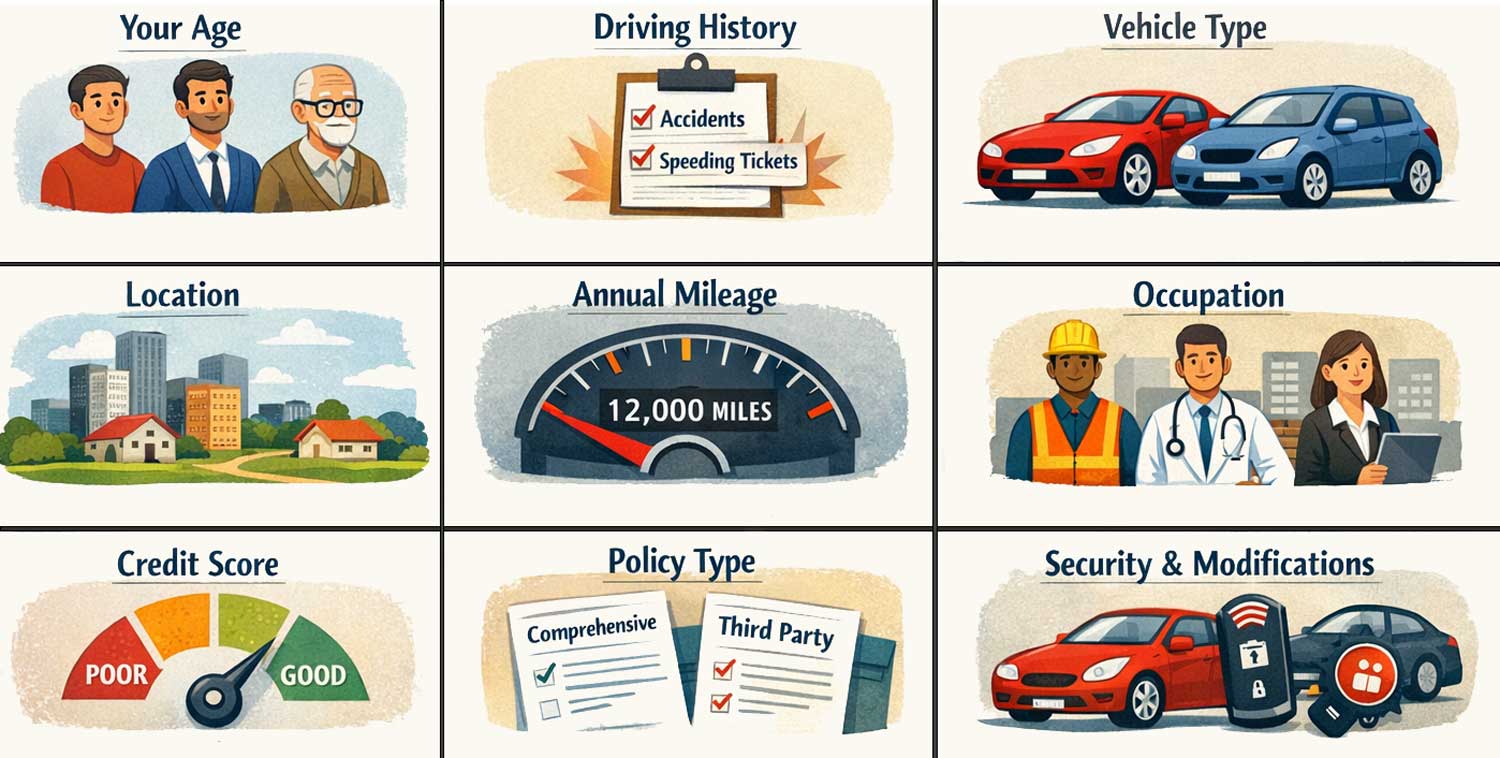
Years of driving experience, claims record and any motoring convictions are central to pricing decisions. A clean driving record over several years may reduce the perceived risk. Previous claims or penalty points may increase it.
Annual mileage and declared usage also feed into the assessment. Social and commuting use is rated differently from business use.
Why prices vary between insurers
Every insurer builds its own pricing model. There is no universal formula. One insurer may apply a more favourable rate to certain occupations but be cautious about particular vehicle types. Another may focus more heavily on postcode risk.
This variation is why two insurers can offer noticeably different premiums for the same driver. The data entered is identical, yet the weighting applied behind the scenes is not.
Insurers weigh these factors differently
That is why the same driver can receive markedly different prices. A quotation is specific to the information supplied and may change if those details change.
Comparing quotations
Because underwriting approaches differ across the market, comparing quotations can expose those differences. A driver who appears expensive with one insurer may be rated more competitively by another.
When reviewing quotations, it is sensible to consider not only the premium but also excess levels, policy limits and cover features. The lowest figure is not always the most suitable option.
Looking at your overall profile
Car insurance pricing is built on the combined effect of many factors rather than a single detail. Your job, where you live, the car you drive, your record on the road and how you use the vehicle all come into the mix. Each insurer looks at those details in its own way when working out a price.